What Is Insurance and How It Works
Introduction
In a world full of uncertainties, one concept provides financial safety, peace of mind, and support during challenging times: insurance. Whether you’re insuring your car, home, health, or life, understanding what insurance is and how it works is essential in today’s financial landscape.
In this comprehensive guide, we’ll explore the definition of insurance, how it works, the types of insurance, benefits, risks, and frequently asked questions—everything you need to understand insurance clearly and confidently.
What Is Insurance?
Insurance is a contractual agreement between an individual (the policyholder) and an insurance company, where the insurer agrees to compensate the insured for specific losses or damages in exchange for a premium.
In simpler terms:
Insurance is a financial safety net that helps you recover from unexpected life events—whether it’s a car accident, health emergency, natural disaster, or loss of income.
Key Components of Insurance
- Policyholder: The person who owns the insurance policy.
- Insurer: The company providing the insurance.
- Premium: The payment you make (monthly/yearly) for the coverage.
- Claim: A formal request to the insurer for payment based on the policy.
- Coverage: The scope of protection offered by the policy.
- Deductible: The amount the policyholder must pay out-of-pocket before the insurance kicks in.

How Does Insurance Work?
Here’s how insurance generally works in four steps:
1. Risk Assessment & Premium Payment
You apply for insurance. The company evaluates the risk of insuring you (based on factors like age, health, location, etc.) and sets a premium accordingly.
2. Policy Activation
Once you pay the premium, your policy becomes active, offering coverage according to the terms specified.
3. Filing a Claim
If an insured event (like an accident or illness) occurs, you file a claim with the insurance provider.
4. Claim Evaluation & Payout
The insurer evaluates the claim and, if it’s valid, provides financial compensation or services based on the policy agreement.
Why Is Insurance Important?
- ✅ Financial Protection: Covers unexpected expenses.
- ✅ Peace of Mind: Reduces stress during emergencies.
- ✅ Legal Requirement: Some insurances, like auto or health, are mandatory.
- ✅ Income Protection: Helps families recover from the loss of a breadwinner.
- ✅ Asset Preservation: Protects properties and possessions from damage or theft.
Types of Insurance
Let’s explore the most common and essential types of insurance:

1. Health Insurance
Keyword: What is health insurance
Covers medical expenses such as doctor visits, hospitalization, prescriptions, and surgeries. In many countries, it’s mandatory or highly encouraged.
Common plans:
- HMO (Health Maintenance Organization)
- PPO (Preferred Provider Organization)
- High-deductible health plans
2. Life Insurance
Keyword: Life insurance explained
Provides a lump-sum payment to your beneficiaries upon your death. It ensures your family’s financial future, covering debts, funeral costs, and income loss.
Types of life insurance:
- Term life insurance (coverage for a specific time)
- Whole life insurance (lifelong coverage + savings)
3. Auto Insurance
Keyword: What does car insurance cover
- Covers damage or theft involving vehicles. Often required by law, it includes:
- Liability coverage (for injury or damage to others)
- Collision coverage
- Comprehensive coverage
- Uninsured motorist protection
4. Homeowners & Renters Insurance
Keyword: Home insurance definition
Homeowners’ insurance protects against damage to your home (fire, theft, weather).
Renters’ insurance covers your personal belongings inside a rented property.
5. Travel Insurance
Covers trip cancellations, medical emergencies abroad, lost luggage, or travel delays.
Tip: Ideal for international trips and adventure travelers.

6. Disability Insurance
Provides income if you’re unable to work due to injury or illness. It comes in short-term and long-term policies.
7. Pet Insurance
Helps cover veterinary bills, surgeries, or chronic conditions for pets.
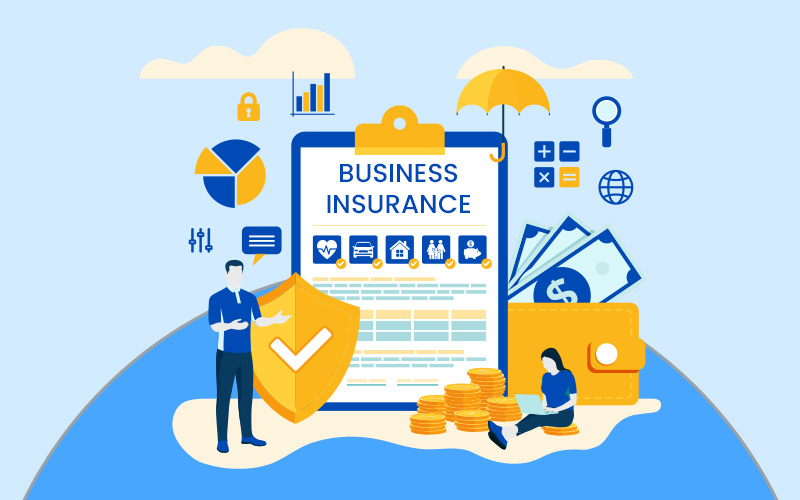
8. Business Insurance
Protects businesses from losses due to property damage, lawsuits, or employee-related risks.
Examples:
- General liability insurance
- Workers’ compensation
- Professional liability (E&O insurance)
How Insurance Premiums Are Calculated
Insurance companies use a process called underwriting to assess the level of risk before issuing a policy.
Factors influencing your premium:
- Age
- Health status
- Driving record
- Occupation
- Location
- Claim history
- Credit score
- Higher risk = higher premiums.
Benefits of Having Insurance
Covers Large Financial Losses
Avoids the burden of out-of-pocket expenses during emergencies.
Promotes Savings
Some policies (like life or retirement insurance) include savings components.
Ensures Business Continuity
Keeps businesses running smoothly even after losses or lawsuits.
Legal Protection
Liability insurance shields you from legal damages.
Improves Loan Eligibility
Banks often require insurance for loans or mortgages.
What Happens If You Don’t Have Insurance?
You could face significant financial loss from unexpected events.
- Legal penalties for driving without auto insurance.
- Limited access to healthcare without health coverage.
- Emotional and financial stress on your family if something happens to you.
- Conclusion: Going uninsured is a gamble that can cost more in the long run.
Insurance and Risk Management
Insurance is a key part of personal and business risk management.
By transferring risk to an insurer, individuals and companies avoid catastrophic losses. Smart insurance planning involves:
- Assessing your risks
- Choosing appropriate coverage
- Reviewing policies annually

Common Myths About Insurance
- ❌ “Insurance is a waste of money if I never file a claim.”
✅ Truth: It’s financial protection—you’re paying for peace of mind and security, not guaranteed usage. - ❌ “Young people don’t need life insurance.”
✅ Truth: Getting life insurance young means lower premiums and protects loved ones early. - ❌ “All policies are the same.”
✅ Truth: Coverage varies widely. Always read the fine print and compare quotes.
How to Choose the Right Insurance
- Assess your needs (e.g., Do you own a car? Do you have dependents?)
- Compare policies and providers for the best value.
- Understand exclusions—what’s not covered matters too.
- Review deductibles and coverage limits.
- Read customer reviews and check ratings.
Pro tip: Use a licensed insurance agent or comparison websites for quotes.
- Future of Insurance: Trends in 2025 and Beyond
- Digital-first insurers offering online claims and paperless policies
- Usage-based insurance (UBI) based on behavior (e.g., driving habits)
- AI and machine learning in risk assessment
Parametric insurance for instant payouts based on set events (like weather conditions)
Frequently Asked Questions (FAQ)
What’s the difference between term and whole life insurance?
- Term: Covers you for a set period (e.g., 20 years), lower cost.
- Whole: Lifelong coverage + cash value, more expensive.
Can I have more than one insurance policy?
Yes, but you cannot claim more than your loss (no profit from insurance).
Is insurance tax-deductible?
It depends. Some policies (like business or health insurance) may offer tax benefits.
When should I update my policy?
- Marriage or divorce
- Birth of a child
- Major purchase (home, car)
- Income change
Final Thoughts
Insurance is not just a financial product—it’s a lifeline during life’s most difficult times. Whether you’re protecting your health, your family, or your assets, having the right insurance in place is a critical part of financial wellness.
Understanding how insurance works empowers you to make smarter decisions, reduce stress, and secure a brighter future.